Popular articles
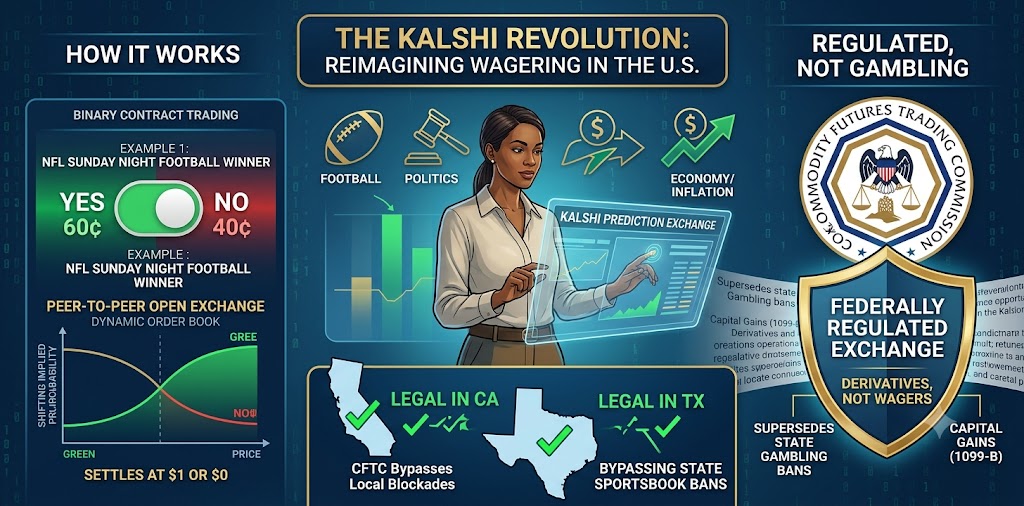

Here's the uncomfortable truth about prediction markets in 2026: 69% of Polymarket users have lost money. A documented trader won 27 out of 53 bets — a 51% win rate — and still lost $2 million.
Being right isn't enough. The market is increasingly dominated by a small group of professionals, automated systems, and institutional capital that have turned prediction markets into something far more competitive than they look from the outside.
That said, real edge exists. This guide covers the seven strategies that actually work — and why most retail traders lose even when they're directionally correct.
The Landscape First: Who You're Actually Trading Against
Before any strategy, you need to understand who's on the other side of your trade.
A 2026 study analyzing $13.76 billion in Polymarket trades found that roughly 3% of accounts are responsible for the vast majority of price-setting moves. These accounts:
- React to public news within seconds, not minutes
- Systematically eliminate pricing gaps between platforms
- Trade against the crowd's behavioral mistakes
The other 97% — including most retail traders — lose money to these 3%. Their losses are what fund the minority's profits. The top 1% of traders capture approximately 76% of all profits on the platform.
This isn't meant to be discouraging — it's meant to help you stop trading like the 97% and start thinking like the 3%.
How Prediction Markets Work: A Complete Beginner's Guide (2026)
Strategy 1: Information Speed Trading
The single biggest edge in prediction markets isn't a clever model. It's being the first person to update a contract when relevant news breaks.
When the Fed announces a surprise rate decision, or a starting quarterback is ruled out 90 minutes before kickoff, or a court ruling comes down — there's a brief window (measured in seconds) where prediction market prices haven't caught up to the news. Traders who catch that window and react immediately can enter at prices that are dramatically mispriced relative to the new reality.
How to execute it
- Set up news alerts for your target market domains: Fed meeting minutes, injury reports, court filings, regulatory announcements
- Use tools like Verso (a Bloomberg-style terminal for Polymarket/Kalshi) or Aeon (an autonomous monitoring agent that fires alerts on probability shifts) to watch contract prices in real time
- The moment news breaks, your job is to evaluate: does this materially change the true probability, and has the market priced it yet?
- If yes, enter fast — these windows close within 2–7 seconds as automated systems reprice
The honest caveat
Manual execution against algorithmic traders is increasingly difficult. On high-liquidity contracts, bot systems will outpace you to the reprice almost every time. This strategy is most viable on lower-liquidity markets — niche political races, obscure regulatory outcomes, specific AI product launches — where automated systems aren't running.
Is Prediction Market Income Taxable? What the IRS Says in 2026
Strategy 2: Domain Expertise Concentration
The most sustainable, and least talked-about, edge in prediction markets is simply knowing more than everyone else in a specific domain.
The top macro traders on Polymarket earned $3.26M+ in early 2026 from concentrated bets on Federal Reserve decisions. They weren't running clever algorithms — they had deep expertise in monetary policy, read the Fed's forward guidance carefully, and consistently priced FOMC outcomes better than the market consensus.
This strategy doesn't require speed or automation. It requires:
- Picking a domain where you genuinely have an edge — a sport you follow obsessively, a political region you understand deeply, an industry where you work professionally
- Building a personal model for that domain — even a simple spreadsheet tracking historical base rates, relevant indicators, and your own probability estimates
- Comparing your estimates to market prices and only trading when there's meaningful disagreement
Domains with the most retail-accessible edge in 2026
- State-level politics: National elections attract massive professional attention; state and local races often don't
- Tech milestone markets: AI model releases, product launches, SpaceX events — professionals in these industries have genuine information advantages
- Niche sports markets: NFL is heavily covered; arena football or minor league sports markets have less professional attention
- Economic subcategories: Core CPI subcomponents are harder to forecast than headline CPI, and markets for them attract fewer sophisticated traders
The key is concentration over diversification. Spreading thin across 30 different event types is a path to average outcomes. Betting deeply in one domain where you're genuinely skilled is how the top traders build real P&L.
Strategy 3: Cross-Platform Arbitrage
When Kalshi and Polymarket price the same event differently, you can lock in a guaranteed profit by buying one side on each platform simultaneously — regardless of which way the event resolves.
How it works
Say Kalshi is pricing "Fed rate cut in October" at 65¢ YES and Polymarket is pricing the same event at 55¢ YES.
- Buy YES at Polymarket: 55¢ per contract
- Buy NO at Kalshi (equivalent to selling YES): 35¢ per contract (since YES is at 65¢)
- Total cost: 90¢ per pair
- Guaranteed payout: $1.00 regardless of outcome
- Gross locked profit: 10¢ per pair
After fees (Polymarket ~1–2%, Kalshi ~1.75% peak), you need a spread of at least 6% for this to be profitable after costs. Below that, fees eat the edge.
The reality in 2026
From April 2024 to April 2025, documented arbitrage extraction across platforms exceeded $40 million — but 75% of that went to the top three automated wallets. Manual arbitrage windows now last 2–7 seconds before algorithmic systems close them.
Tools that make this accessible:
- Matchr: Aggregates 1,500+ markets across platforms, flags arbitrage opportunities with smart routing
- Oddpool: Cross-venue data with live arbitrage detection and orderbook depth
- OddsPapi: Unified API across Polymarket, Kalshi, and 350+ sportsbooks with real-time WebSocket feeds
Minimum viable setup: Funded accounts on both Kalshi and Polymarket ($2,000–$5,000 each), plus API monitoring. Without automation, you'll rarely catch windows before they close.
Strategy 4: Behavioral Contrarianism
The crowd is wrong in predictable ways. Identifying and trading against those systematic errors is one of the most documented edges in prediction market research.
Favorite-longshot bias
In political prediction markets, favorites are consistently overpriced and longshots are consistently underpriced. A candidate with a true 70% win probability will often trade at 72–75¢ because retail money piles into perceived front-runners.
The systematic trade: when a high-probability contract trades at 5+ points above your estimated true probability, sell it. This has been documented as profitable across multiple election cycles.
Panic overreaction fading
When major news breaks — an unexpected poll, a regulatory ruling, an injury — the crowd often overreacts in the first minutes. Contract prices whipsaw dramatically before settling at a new equilibrium.
The contrarian play: wait for the whipsaw peak, then take the opposite side. If a candidate's YES contract drops from 70¢ to 45¢ on ambiguous bad news, the true probability shift might only justify a drop to 62¢. The 17¢ overreaction is your opportunity.
Reverse line movement in sports
When 70%+ of public money is on one side of a sports contract but the price moves the other direction, that's sharp money — sophisticated traders betting the other way with enough size to move prices despite the public flow. Following reverse line movement (fading the public and tracking where prices actually move) is one of the most reliable sports market signals.
Crowd sentiment monitoring tools
- PolyTale: AI-powered research agent with real-time whale tracking and crowd sentiment analysis
- Kairos: Unified orderbook view across Kalshi and Polymarket with visible order flow
Strategy 5: Passive Market-Making
Most traders think about taking positions on outcomes. Market-makers think about something different: earning the spread on both sides by posting limit orders and letting other traders cross them.
On Kalshi's NFL markets, passive resting limit orders earned an aggregate $29 million in profit over one season — not by being right about game outcomes, but by consistently sitting on the bid and ask and collecting the spread from more impatient traders.
How it works
Instead of buying YES at the current market price, you post a limit order slightly below it. Instead of selling YES at market, you post a limit order slightly above. Other traders who want immediate execution will cross your spread.
Your profit = the spread between your buy and sell prices, collected over thousands of small transactions.
Requirements to do it well
- Capital: Market-making requires capital sitting on both sides simultaneously — typically $5,000+ per market to be meaningful
- Risk management: You're holding inventory (contracts) that have directional exposure until they get filled on the other side. Requires careful position limits per market
- Platform fit: Works better on Kalshi (USD, traditional order book) than Polymarket (USDC, higher withdrawal friction)
- Market selection: Stick to mid-liquidity markets — too liquid and professional market-makers outcompete you; too illiquid and you can't fill positions
This strategy requires lower directional skill but higher operational sophistication. It's the most consistent earner in the long run for traders who invest in the infrastructure.
Strategy 6: Kelly Criterion Position Sizing
Most traders, even those with genuine edge, lose money because of position sizing errors — not because they're wrong about outcomes.
The Kelly Criterion is a mathematical formula for optimal bet sizing that maximizes long-run bankroll growth without risking ruin:
f = (bp - q) / b*
Where:
- f* = fraction of bankroll to bet
- b = net odds (payout per unit risked)
- p = your estimated win probability
- q = 1 - p (loss probability)
A worked example
You estimate a 60% chance that the Fed cuts rates in October. The market prices it at 52¢ (implying 52% probability). You're buying YES at 52¢, which pays $1.00 if correct — net odds b = 0.48/0.52 = 0.923.
Full Kelly:
f* = (0.923 × 0.60 - 0.40) / 0.923 = (0.554 - 0.40) / 0.923 = 16.7% of bankroll
That feels like a lot — and it is. Full Kelly maximizes growth but creates roughly a 1-in-3 chance of halving your bankroll before you double it. In practice, fractional Kelly (0.25x or 0.5x) is recommended:
- Half Kelly: 8.4% of bankroll
- Quarter Kelly: 4.2% of bankroll
Practical sizing rules for prediction market traders
- Never risk more than 2–5% of total capital on a single contract (quarter Kelly equivalent for moderate edges)
- Never deploy more than 30–40% of capital simultaneously — keep dry powder for better opportunities
- Size down when uncertain: If your edge estimate is soft, use 0.1x Kelly or less
- Capital lockup: Factor in time-to-resolution — a 3% edge locked for 6 months is a 6% annualized return, which needs to beat your opportunity cost
The single biggest position-sizing mistake retail traders make: betting 10–20% of bankroll on a single contract. Kelly math says this is only justified when your edge is enormous and your probability estimate is extremely confident — rare conditions.
Strategy 7: Bayesian Updating in Political Markets
Political prediction markets are the most researched category — and one of the most exploitable, because most retail participants trade on vibes and narrative rather than systematic probability updating.
The Bayesian approach treats market prices as a starting point (your prior) and updates them systematically as new information arrives.
The workflow
Step 1: Establish your prior
Start with the current market price as an informative baseline (or use historical base rates for similar events as an uninformative prior for novel situations).
Step 2: Identify your information sources
- Polling aggregators (FiveThirtyEight, RealClearPolitics)
- Structural models (economic fundamentals, incumbency data)
- Expert judgment from domain specialists
- Market prices on correlated contracts
Step 3: Update sequentially as data arrives
When a new poll drops showing Candidate A at 54% instead of the expected 51%, use Bayes' rule to update your posterior probability estimate. Compare to the market price — if the market hasn't adjusted, that's your entry window.
Step 4: Exploit the lag
Markets reprice new polling data slowly — typically 15–60 minutes for smaller markets, occasionally hours for niche state-level races. Traders who process new data first capture the alpha from this repricing delay.
Avoiding favorite-longshot bias in political markets
When calculating your probability estimate, deliberately adjust for the documented favorite-longshot bias:
- If your model says 72%, consider 68–70% as your trading price
- If your model says 15%, consider 17–19%
This systematic correction for market mispricing has been documented as profitable across multiple electoral cycles.
Why Most Retail Traders Lose (Even When They're Right)
Understanding the failure modes matters as much as understanding the strategies. Here's what the data shows:
Bad entry prices
Being right about direction is worthless if you enter at terrible prices. A contract priced at 65¢ on a true 60% probability event is already overpriced by 5 cents. Buying it means you need to be right 65% of the time to break even — not 60%.
Retail traders chronically enter at market price without checking whether that price is accurate relative to their own probability estimate.
Overconcentration
A single trader won 51% of bets and lost $2 million because position sizes were wildly inconsistent. Wins were small; losses were catastrophic. Kelly math says your worst bet should be sized for your lowest-confidence edge — retail traders often do the opposite, betting big when they "feel most sure."
Capital lockup blindness
A 4% profit on a contract sounds good until you realize it was locked up for four months. That's a 12% annualized return — good, but only if it was better than your next-best use of that capital. Most retail traders never run this calculation.
Treating prediction markets like sports betting
In sports betting, a $110 bet wins $100. The house has a built-in edge. The goal is just to beat the vig.
In prediction markets, contracts are priced at true probability. There's no guaranteed house edge — but there's also no guaranteed positive expectation from simply taking the other side of overpriced contracts. You need an actual informational or analytical edge, not just contrarianism.
Building Your First Trading System: A Starter Framework
- Pick one domain where you have genuine knowledge advantages
- Track your estimated probabilities in a spreadsheet before checking market prices — this forces you to form independent views rather than anchoring to market consensus
- Only trade when your estimate differs from market price by 5+ points after adjusting for your uncertainty
- Size with quarter Kelly — 25% of your full Kelly recommendation per trade
- Set a monthly loss limit (10–15% of starting capital) and stop if you hit it — this forces a review before continuing
- Track every trade with your entry price, your estimated true probability, and the outcome — over 100+ trades, this data will tell you where your real edge is (or isn't)
The goal isn't to win every trade. It's to develop a repeatable process with a measurable edge, then scale that edge gradually as it proves itself.
Tools to Get Started
Kairos: Aggregates orderbooks across Kalshi and Polymarket for multi-platform order routing.
Verso: A Bloomberg-style terminal delivering real-time data, analytics, and market news.
Oddpool: Tracks odds across multiple venues to flag arbitrage opportunities and spread gaps.
Matchr: Compares prices across 1,500+ markets to find the best rates.
PolyTale: Uses AI to monitor whale positions, crowd sentiment, and market intelligence.
Aeon: Automated monitoring agent that sends probability-shift alerts for news-driven trades.
OddsPapi: A single API connecting Polymarket, Kalshi, and over 350 sportsbooks for custom tools and data feeds.
Frequently Asked Questions
Can a beginner actually make money on prediction markets?
Yes, but the bar is higher than it looks. Beginners with genuine domain expertise in a specific niche (their profession, a sport they follow obsessively) can find real edge. Generic "I think X will happen" betting without systematic probability estimation is likely a losing proposition.
How much capital do you need to get started?
You can open a Kalshi account with as little as $10, but meaningful trading (with proper Kelly sizing and multiple positions) realistically requires $500–$2,000 minimum to see results that aren't dominated by flat fees.
Is automated trading allowed on Kalshi and Polymarket?
Both platforms offer APIs. Automated trading is permitted. Polymarket's CLOB API supports fully automated execution with wallet authentication. Kalshi offers a similar API. Many top traders run fully automated systems.
Are prediction market strategies similar to options trading strategies?
There are parallels — binary options, in particular, have structural similarities to prediction market contracts. Position sizing, probability estimation, and the concept of implied vs. true probability all transfer. But prediction markets lack the greeks (delta, theta, vega), so the risk management frameworks differ.
How do I know if my edge is real or luck?
At minimum, 200–300 trades are needed to distinguish skill from variance in a market with ~60% win rates. Track your predicted probability vs. your actual win rate across trade categories — if you're consistently winning 60%+ in markets where you predicted 60%, you have real edge. If you're consistently winning 50% in markets where you predicted 65%, you're overconfident.
The Bottom Line
Prediction markets in 2026 are not a lottery. They're a competitive information market where 3% of sophisticated participants capture most of the profits — and understanding that reality is the first step toward being on the right side of it.
The strategies that work are consistent:
- Speed when you can react to news faster than other participants
- Domain expertise when you know something better than the market does
- Systematic sizing so a string of losses doesn't end your career before your edge plays out
- Behavioral discipline so you don't trade your emotions when the crowd panics
The strategies that don't work: casual participation, random diversification, market-order entries without probability analysis, and oversized bets on "sure things."
Start with one domain. Build a model. Track every trade. Give it 200 bets before drawing conclusions.
Subscribe to unlock premium content
Sed at tellus, pharetra lacus, aenean risus non nisl ultricies commodo diam aliquet arcu enim eu leo porttitor habitasse adipiscing porttitor varius ultricies facilisis viverra lacus neque.